
Getting workers compensation insurance begins with one document. The ACORD 130. Whether you are an agent preparing a submission or a business owner trying to figure out what your broker is asking for this guide explains what the ACORD 130 form is, how it works what information you must include and where mistakes often happen.
The ACORD 130 form is the Workers’ Compensation Application used across the United States. Insurance agents or brokers fill it out. Send it to insurance carriers. These carriers use the form to assess risk and determine the cost of the policy. The form collects details like payroll broken down by job classification, ownership information, past insurance experience and any history of claims. All of which help shape the final price of the policy.
Table of Contents
What Is the ACORD 130 Form?
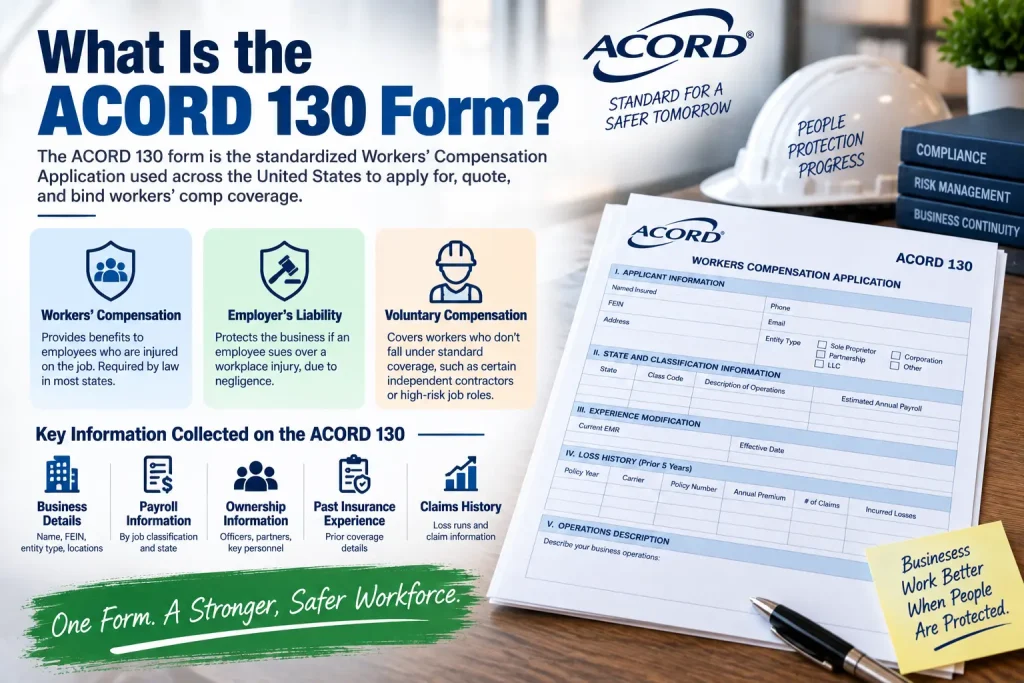
ACORD 130 form is a workers’ compensation application form created and maintained by ACORD Corporation, the nonprofit standards body that oversees data exchange across the insurance industry. Carriers accept it as the primary submission document for quoting and binding workers’ comp coverage.
The ACORD 130 form covers three types of coverage: workers’ compensation, employer’s liability and voluntary compensation. Workers’ compensation is required by law in states and provides benefits to employees who are injured on the job. Employer’s liability protects the business if an employee sues over a workplace injury, due to negligence. Voluntary compensation covers workers who don’t fall under coverage, such as certain independent contractors or employees in high-risk jobs.
One state-specific note worth knowing early: Florida doesn’t use the standard ACORD 130 form. Florida submissions require the ACORD 130 form FL a separate, state-specific version. Agents working across multiple states should confirm which form applies before starting.
Why Underwriters Rely on It
Workers’ comp premium isn’t guesswork. It follows a formula:
Premium = (Payroll ÷ 100 × Class Rate) × Experience Modification Rate
Every number in that equation comes from the ACORD 130. The payroll figures, the classification codes that set the hazard rate, and the experience modification rate (EMR) all of it flows from how the form is completed. If any of those figures are off, the quote is off. That’s why underwriters treat the ACORD 130 form as a primary source document, not just a formality.
It also creates the paper trail needed for audits, renewals, and regulatory compliance.
Who Completes It and Who Uses It
| User | Role |
|---|---|
| Independent agents and brokers | Prepare and submit the form to carriers |
| Underwriters and MGAs | Review the submission to set terms and premium |
| Business owners and HR managers | Supply payroll, classification, and claims data |
| Assigned risk plans | Require the form when voluntary coverage isn’t available |
In practice, the agent or broker builds the form, working with the insured’s payroll or HR team to pull accurate figures. The business owner signs it before it goes to market.
How to Complete the ACORD 130 form
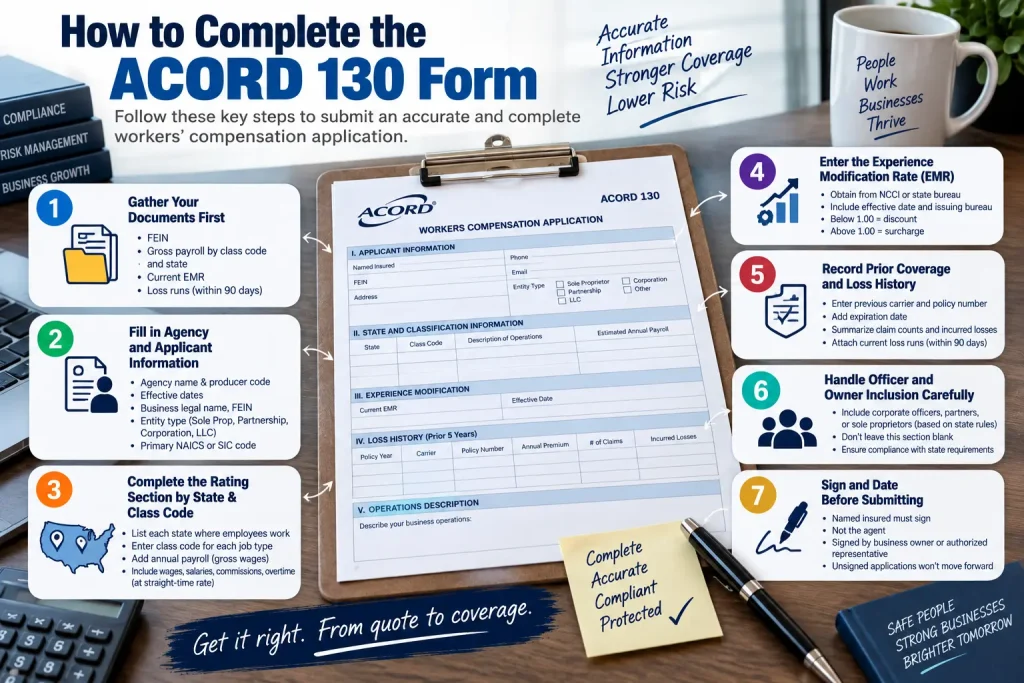
- Gather your documents first. You need the insured’s Federal Employer Identification Number (FEIN), gross payroll broken down by class code and state, the current EMR with its effective date and issuing bureau, and loss runs valued within the last 90 days. Missing any of these before you start typically means restarting later.
- Fill in agency and applicant information. Enter the agency name, producer code, and desired effective dates. For the business, record the legal name, FEIN, address, entity type sole proprietor, partnership, corporation, or LLC and the primary NAICS or SIC code that best describes operations.
- Complete the rating section by state and class code. List every state where employees work, the class code for each type of job, and the corresponding annual payroll. Payroll must be gross remuneration, not net wages. One of the important parts of this form is the payroll section. This includes wages, salaries, commissions and overtime. But overtime is reported at the straight-time rate, not the overtime rate. This section is critical because it feeds directly into how the premium’s calculated. Any error here can lead to underwriting issues or even incorrect pricing. That’s why accuracy matters more in this area than else on the form.
- Enter the Experience Modification Rate. The EMR comes from NCCI which administers classification rules in 35 states and Washington D.C. or from the applicable independent state bureau. An EMR below 1.00 reduces premium; above 1.00 increases it. A 1.35 EMR adds a 35% surcharge. Accounts with very high EMRs often can’t access the voluntary market and must go through assigned risk plans instead.
- Record prior coverage and loss history. Enter the previous carrier, policy number, and expiration date. Summarize claim counts and total incurred losses for the required prior years, and attach current loss runs as supporting documentation.
- Handle officer and owner inclusion carefully. Whether corporate officers, partners, or sole proprietors must be included in coverage depends on state rules and entity type. This section is commonly skipped or left vague which forces underwriters to make assumptions and often results in the form being returned.
- Sign and date before submitting. The named insured must sign. Not the agent the business owner or an authorized representative. An unsigned application doesn’t move forward.
ACORD 130 Form vs. Related Forms
| Form | Purpose | When It’s Used |
|---|---|---|
| ACORD 130 | Workers’ comp application | Standalone WC submissions |
| ACORD 125 | General commercial application | Multi-line submissions only |
| ACORD 130 FL | Florida WC application | Required in Florida instead of ACORD 130 |
The ACORD 125 is the one that causes the most confusion. It’s not required when workers’ comp is the only line being quoted the ACORD 130 form handles that on its own. The 125 comes in when a broker is submitting multiple commercial lines at once and needs a master application to tie everything together.
Common Mistakes to Avoid
- Reporting net instead of gross payroll — Workers’ comp is rated on gross wages. Using net figures understates exposure and often triggers significant audit adjustments after the policy period closes.
- Using the wrong class code Class codes are set by NCCI or the state bureau and represent specific types of work. A roofing crew coded as clerical staff is a serious misrepresentation that will be caught at audit.
- Submitting outdated loss runs Most carriers want loss runs valued within 90 days. Older documents get rejected, which delays the whole submission.
- Skipping the officer inclusion section This section has real coverage and premium implications. Leaving it blank is one of the most common reasons forms come back incomplete.
- Missing the FEIN Without it, underwriters can’t verify the EMR through NCCI. No verified EMR usually means no quote.
Frequently Asked Questions
Does the ACORD 130 Form always need the ACORD 125 attached?
No. For a standalone workers’ compensation submission, the ACORD 130 form is complete on its own. The ACORD 125 is only needed when multiple commercial lines are being quoted together — it functions as a general cover application in those cases, with the 130 attached as a supplement.
Where does the Experience Modification Rate come from?
The EMR is calculated by NCCI or an independent state bureau based on the insured’s actual loss history compared to expected losses for their industry class. It’s linked to the business’s FEIN, which is why that number is required on the form. An EMR of 1.00 is baseline — below that is a discount, above it is a surcharge.
How is payroll handled for businesses in multiple states?
List each state, its applicable class codes, and employee payroll. Since workers’ comp rules and rates vary by state, assigning employees to the correct state is essential for accurate pricing and compliance.
Can errors be corrected after the policy is bound?
Yes, though the process depends on the carrier. Pre-binding corrections mean resubmitting an updated form. Post-binding corrections typically require an endorsement. Payroll errors discovered during the final audit are settled through the audit process — either as additional premium owed or a return premium, depending on whether payroll was understated or overstated.