
ACORD 131 is a form in the world of business insurance especially when companies need extra protection beyond their main policies. It helps fill the gap between what a primary policy covers and what the business truly needs. This form is used to apply for umbrella or excess liability coverage, which kicks in when claims go over the limits of liability, commercial auto or workers compensation policies.
ACORD 131, officially titled the Umbrella/Excess Section, is the standardized supplemental form used to apply for umbrella or excess liability insurance above a business’s primary policies. It must always be submitted alongside ACORD 125. The form captures requested coverage limits, self-insured retention, coverage type, and a full schedule of existing underlying liability policies. Without a complete, accurate ACORD 131, umbrella or excess coverage cannot be quoted or bound.
Table of Contents
What Is ACORD 131?
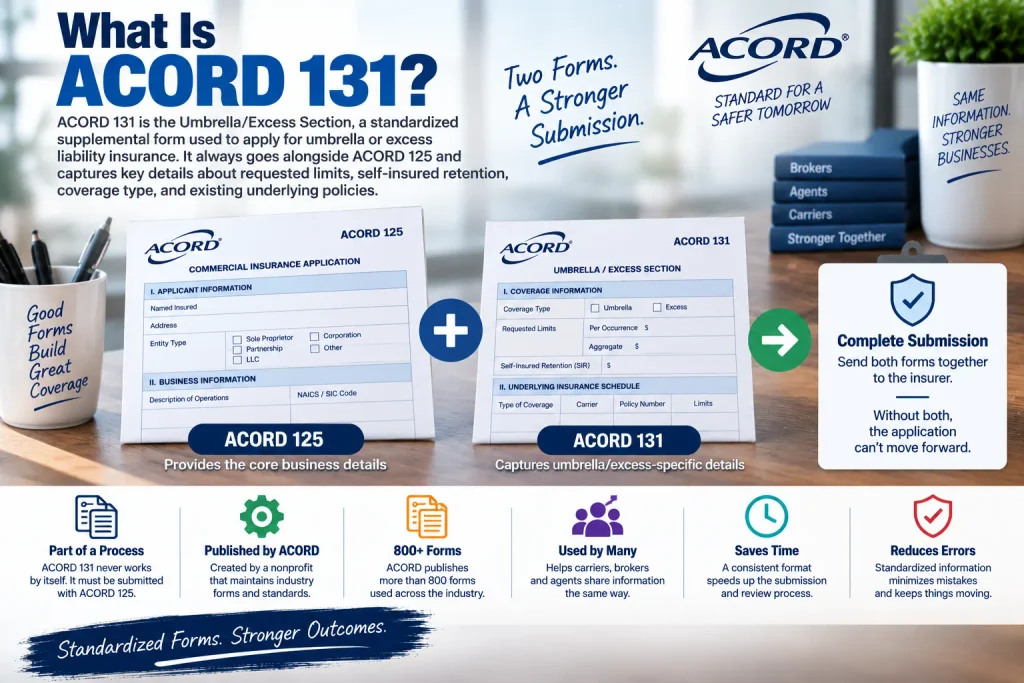
The form is part of a process. It never works by itself. Instead it always goes alongside ACORD 125 which holds the business details. Together these two forms make up a submission package. The agent must complete both. Send them together to the insurer. Without both the application can’t move forward.
ACORD 131 is published by ACORD, a nonprofit that keeps the insurance industry running smoothly with forms. They have over 800 forms used widely across the sector. These forms help carriers, brokers and agents share information the way. That consistency saves time. Cuts down on errors.
Why Is ACORD 131 Used?
Excess and umbrella underwriting works differently from primary policy underwriting. The excess carrier prices off the adequacy of the layers beneath it rather than evaluating the business’s ground-level exposure directly. ACORD 131 delivers a clear, structured picture of underlying coverage in a consistent format every underwriter expects.
Market growth makes this form more relevant each year. The U.S. excess liability market was approximately $34.1 billion in 2023 and is forecast to reach $48.5 billion by 2031. With over 6.3 million commercial umbrella policies active globally in 2025, a 19% increase since 2023 clean, complete submissions are the only practical way to keep pace with rising volume.
Who Uses ACORD 131?
ACORD 131 is used by insurance agents and brokers on behalf of commercial clients seeking umbrella or excess liability coverage. It applies strictly to commercial lines personal umbrella policies follow entirely separate processes.
This form is used often by businesses in high-risk fields like construction, transportation, healthcare and manufacturing. These industries face lawsuits and higher exposure. Clients in these areas often have contracts that require them to carry umbrella limits above amounts. That’s why ACORD 131 is so important here. SME adoption of commercial umbrella policies also rose 29% between 2023 and 2025, driven by simplified digital platforms expanding the pool of ACORD 131 users well beyond large corporate accounts.
How Does ACORD 131 Work?
The underwriter checks the submission carefully. They look at the policy schedule first. If any information is missing or doesn’t match the application can get stuck. One small mistake. Like a wrong business name or a missing policy. Can delay things for days. That means clients might not get the coverage they need when they need it.
The underwriter checks the submission carefully. They look at the policy schedule first. If any information is missing or doesn’t match the application can get stuck. One small mistake. Like a wrong business name or a missing policy. Can delay things for days. That means clients might not get the coverage they need when they need it.
What Information Is Required?
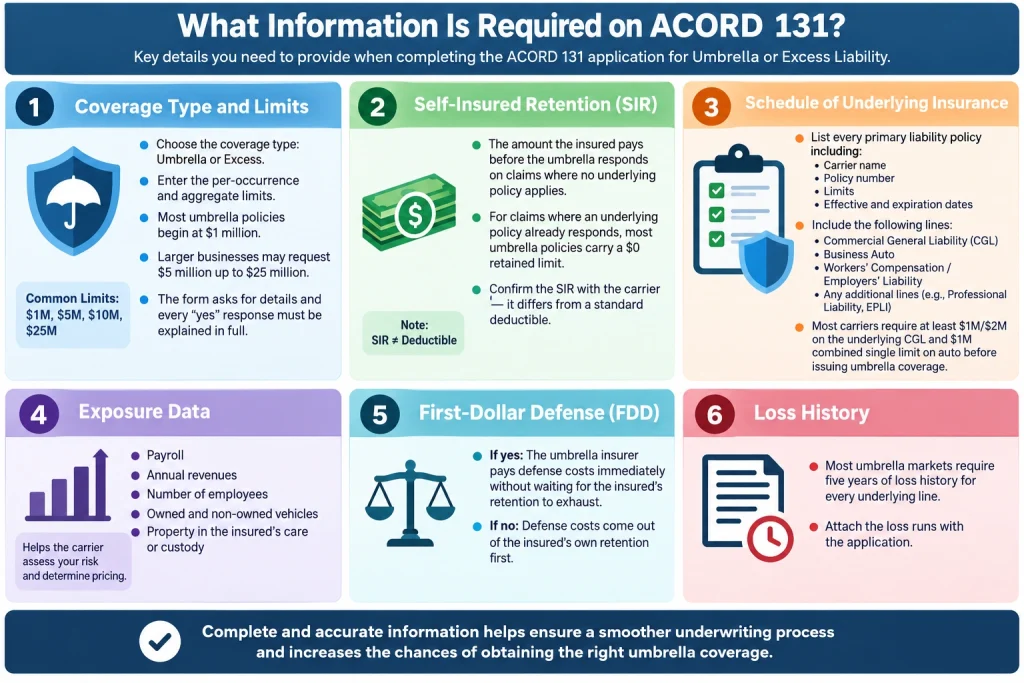
Coverage Type and Limits: When filling out ACORD 131 start by choosing the coverage type. Umbrella or excess. Then enter the per-occurrence and limits. Most umbrella policies begin at $1 million. Larger businesses might ask for $5 million up to $25 million. The form asks for details and every yes response must be explained in full.
Self-Insured Retention (SIR): The amount the insured pays before the umbrella responds on claims where no underlying policy applies. For claims where an underlying policy already responds, most umbrella policies carry a $0 retained limit. Confirm the SIR with the carrier it differs from a standard deductible.
Schedule of Underlying Insurance: Every primary liability policy must be listed carrier name, policy number, limits, and effective and expiration dates covering CGL, Business Auto, Workers’ Compensation/Employers’ Liability, and any additional lines such as professional liability or EPLI. Most carriers require at least $1M/$2M on the underlying CGL and $1M combined single limit on auto before issuing umbrella coverage.
Exposure Data: Payroll, annual revenues, number of employees, owned and non-owned vehicles, and property in the insured’s care or custody.
First-Dollar Defense (FDD): If yes, the umbrella insurer pays defense costs immediately without waiting for the insured’s retention to exhaust. If no, defense costs come out of the insured’s own retention first.
Loss History: Most umbrella markets require five years of loss history for every underlying line attached with the application.
ACORD 131 vs. Related Terms
Umbrella vs. Excess: An umbrella policy can drop down and cover certain claims not addressed by any underlying policy, subject to a self-insured retention. An excess policy strictly follows the underlying form and only adds limits, it will not fill coverage gaps. Selecting the wrong type on ACORD 131 signals a product misunderstanding to the underwriter.
ACORD 131 vs. ACORD 125: ACORD 125 captures general business information entity name, address, and operations. ACORD 131 handles umbrella and excess-specific details. The named insured on both forms must match exactly, character for character.
ACORD 131 vs. ACORD 126 and ACORD 130: ACORD 126 documents general liability; ACORD 130 covers workers’ compensation. Limits on these underlying forms must match what is listed on the ACORD 131 schedule. Any discrepancy triggers underwriter questions before a quote is issued.
Common Mistakes
Incomplete underlying schedule. Leaving blank fields is the most common reason underwriters return applications. Every policy needs a carrier name, policy number, limits, and dates.
Blank fields instead of N/A. Always mark “N/A” or “None” rather than leaving sections empty. A blank field raises questions about whether the producer forgot.
Unexplained yes responses. The form requires a detailed explanation for every yes response. Checking yes without details forces the underwriter to pause quoting and request the missing information separately.
Mismatched entity names. The named insured must be identical across ACORD 125 and ACORD 131. Any variation creates a coverage ambiguity underwriters will flag.
Stale renewal data. Renewal submissions require updated underlying schedules, current exposure data, and refreshed loss history. Resubmitting prior-year data unchanged risks the renewal being quoted on inaccurate information.
Frequently Asked Questions
Is ACORD 131 always required for umbrella submissions?
Yes. Any commercial umbrella or excess application requires ACORD 131 paired with ACORD 125. Submitting one without the other results in immediate rejection, including on renewals.
Should professional liability or EPLI be listed in the underlying schedule?
If those policies are part of the coverage tower the umbrella sits above, list them. When in doubt, include them and let the underwriter decide. Omitting a policy creates a potential gap that could surface at claim time.
What is the difference between an SIR and a deductible?
A self-insured retention applies when the umbrella drops down to cover a claim no underlying policy addresses. A deductible applies to covered claims on a primary policy. Most umbrella policies carry a $0 SIR for claims where an underlying policy already responds.
Where can I get the current ACORD 131 form?
Official ACORD forms are available through the ACORD website, typically requiring membership or a license. Most agents access them through licensed agency management systems. Always confirm which edition your target carrier accepts before submitting.